Do limited companies need an accountant?
Overview
Limited companies are not legally required to hire an accountant. Directors can prepare their own bookkeeping, annual accounts and Corporation Tax returns. However, directors remain legally responsible for filing accurate returns on time, which is why most limited companies outsource at least some accounting tasks. Learn about these accounting obligations, the difficulty to directors each poses, and which tasks are most cost-effective to outsource.
For broader guidance on whether to hire support with your finances, see our guide Do You Need an Accountant?
Financial obligations
Annual Accounts
A set of financial statements containing a balance sheet, profits and losses
Corporation Tax Return (CT600)
A tax return stating the company's taxable profits and reliefs claimed
Corporation Tax Payment
The Payment of the Corporation Tax liability calculated in the CT600
Bookkeeping records
A list of records containing sales invoices, purchase invoices and expenses
Director transaction records
A list of records containing director salaries, dividends, expenses and loans
Obligation difficulty
| Time | Expertise | Difficulty | |
|---|---|---|---|
| Bookkeeping | High | Medium | Moderate |
| Payroll (PAYE)* | Medium | Medium | Moderate |
| Annual Accounts | Low | High | Hard |
| Corporation Tax Return (CT600) | Low | High | Hard |
| Corporation Tax Payment | Low | Medium | Moderate |
| Confirmation Statement (CS01) | Low | Low | Easy |
| Director records (dividends, loans, etc.) | Medium | Medium | Moderate |
| VAT Returns* | Medium | Medium | Moderate |
The hybrid approach
Budget conscious directors commonly manage the easy to moderate tasks in-house and outsource those specialist tasks which require technical expertise and carry risk. In practice, this typically means directors record day-to-day sales and purchase invoices, manage payroll, and handle bookkeeping. At the end of the financial year, an accountant will be appointed to handle annual accounts and CT600 submission.
This helps to keep accounting bills down, though it is not always net cost-effective.
The managed approach
Where directors are high-value earners for their companies, time spent handling finances has an opportunity cost. Take these three directors:

James, Sales Lead
Converts prospects into paying customers
Bianca, Consultant
Sells valuable expertise to clients
Treesha, Creative Director
Launches products that increase revenue
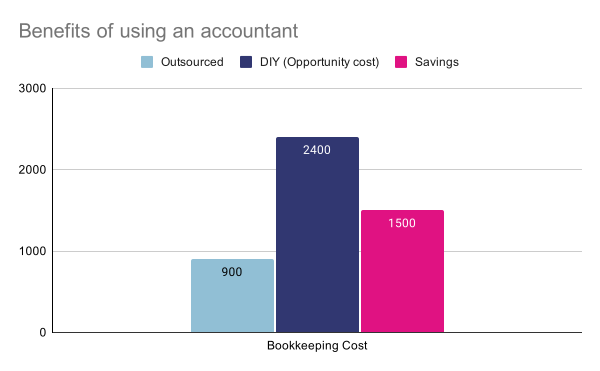
Let’s assume James' time is worth £100 per hour. He can either carry out his own bookkeeping, which takes 2 hours a month, or use his accountant who charges £75 a month. In this scenario, annual bookkeeping costs £900 to outsource, or 24 hours of James’ time. This time represents an opportunity cost of £2,400. Here, hiring a bookkeeper represents a potential saving of £1,500 per year. For directors who are important revenue generators, outsourcing routine finances can be the more cost-effective option.
Common questions
Basic year-end accounts typically cost £500-£1,000 per year. Ongoing accounting, including bookkeeping and tax support, usually ranges from £75-£300+ per month, depending on the size and complexity of the business.
Usually not. Most small companies don’t file a profit and loss account with Companies House, but one is still required for HMRC.
Yes. Limited companies pay Corporation Tax on taxable profits from their first accounting period.
Most limited companies must keep accounting records for at least 6 years after the end of the relevant accounting period.
Companies usually need to meet or stop meeting the small company thresholds for two consecutive years before reporting requirements change.
No. It’s not a legal requirement, but many business owners use one to save time, reduce risk and stay compliant. For more guidance on whether your business suits an accountant, see our guide Do You Need an Accountant?